Keep family nearby
Create a separate living space for relatives, caregiving, or guests.
Meet West Coast Construction Pro, LoanTree's ADU construction partner.
Construction service areas
Sacramento Metro Area, CA
Bay Area, CA
West Coast Construction Pro and LoanTree are separate companies. Contractor selection, construction agreements, permitting, and loan approval are separate decisions and processes.
Visit construction partner
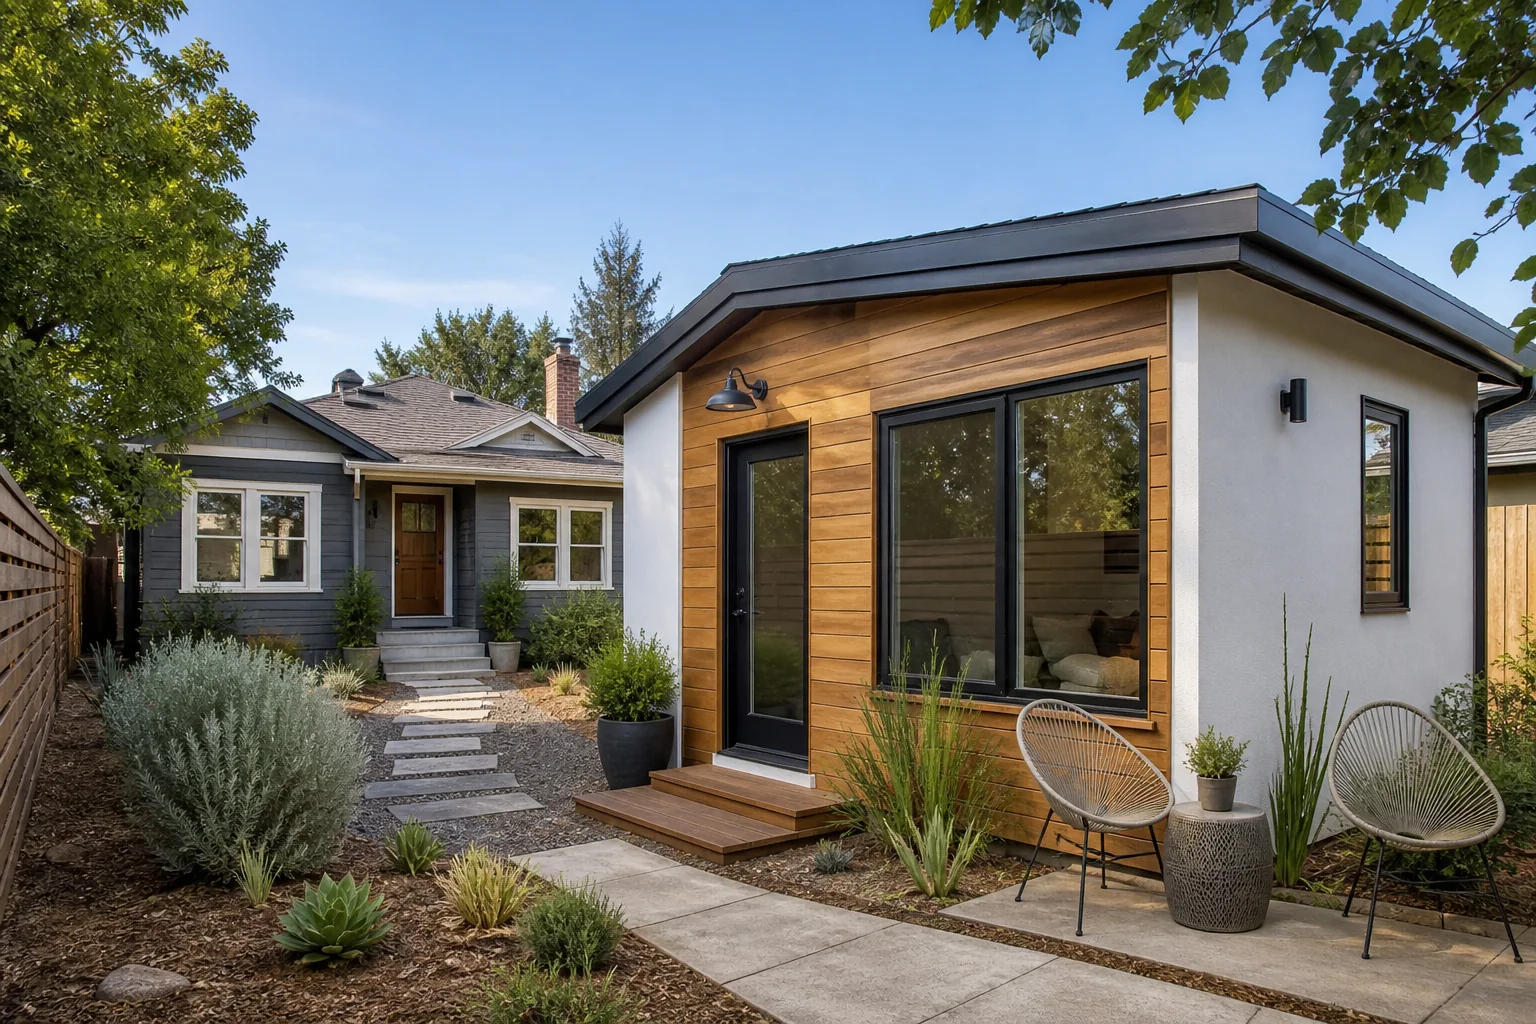
An accessory dwelling unit is an independent living space on the same property as a primary home.
Create a separate living space for relatives, caregiving, or guests.
Add a possible long-term rental while planning for vacancy, upkeep, insurance, and taxes.
A permitted ADU may improve marketability or appraised value, but the result depends on the property and local market.
A separate backyard cottage on the same property.
An independent living space connected to the main home.
A garage, basement, or other existing area converted for living.
A smaller unit created within a single-family residence.
Each option uses your home equity differently. Compare how the money arrives, what happens to your mortgage, and how the payment may change.
| Compare | HELOAN/Second Mortgage | Cash-Out Refinance | HELOC |
|---|---|---|---|
| How It Funds the Project | Receive one lump sum that can fund a defined ADU budget while keeping your current first mortgage. | Replace your first mortgage with a larger loan and receive cash for the ADU at closing. | Open a revolving second mortgage and draw funds as design, permits, and construction costs arise. |
| Mortgage Impact | Make a separate monthly payment alongside your current mortgage payment. | Make one new mortgage payment based on the full new balance, rate, and term. | Make a separate payment that can change with your balance and market rates. |
| Project Fit | Match predictable proceeds to a project with a clear scope and budget. | Combine the amount borrowed for the ADU and your existing mortgage into one loan payment. | Borrow in stages instead of receiving the full available line at once. |
| Rate Type | Usually fixed. | Fixed or adjustable, depending on the mortgage you select. | Usually variable. |
Some projects may also use renovation or construction financing, which can require approved plans, a contractor budget, an appraisal, and managed draws.
Available equity can help frame an ADU budget. Approval and usable proceeds depend on the borrower, property, liens, appraisal, and loan terms.
Review home equity optionsAdjust your home value and current mortgage balance.
California streamlines many ADU applications, but local building, fire, utility, site, coastal, and use rules still apply.
Confirm current requirements with your city or county before paying for final plans or committing to a construction schedule.
Read California's current ADU handbookThis page provides general information, not legal, tax, appraisal, construction, or loan approval advice.
Decide whether the ADU is for family, long-term rental, guests, or flexible space.
Ask the local planning department and contractor about the site, utilities, fire access, and permit path.
Include design, engineering, permits, site work, utility connections, construction, finishes, and contingency.
Review the current mortgage, available equity, project schedule, loan costs, and payment structure together.
Bring your property, estimated budget, current mortgage, and project stage. We can help you compare the next financing step.
Choose a convenient time for a Google Meet with a LoanTree advisor.